The Investor’s Marshmallow Test
Dear Clients and Friends,
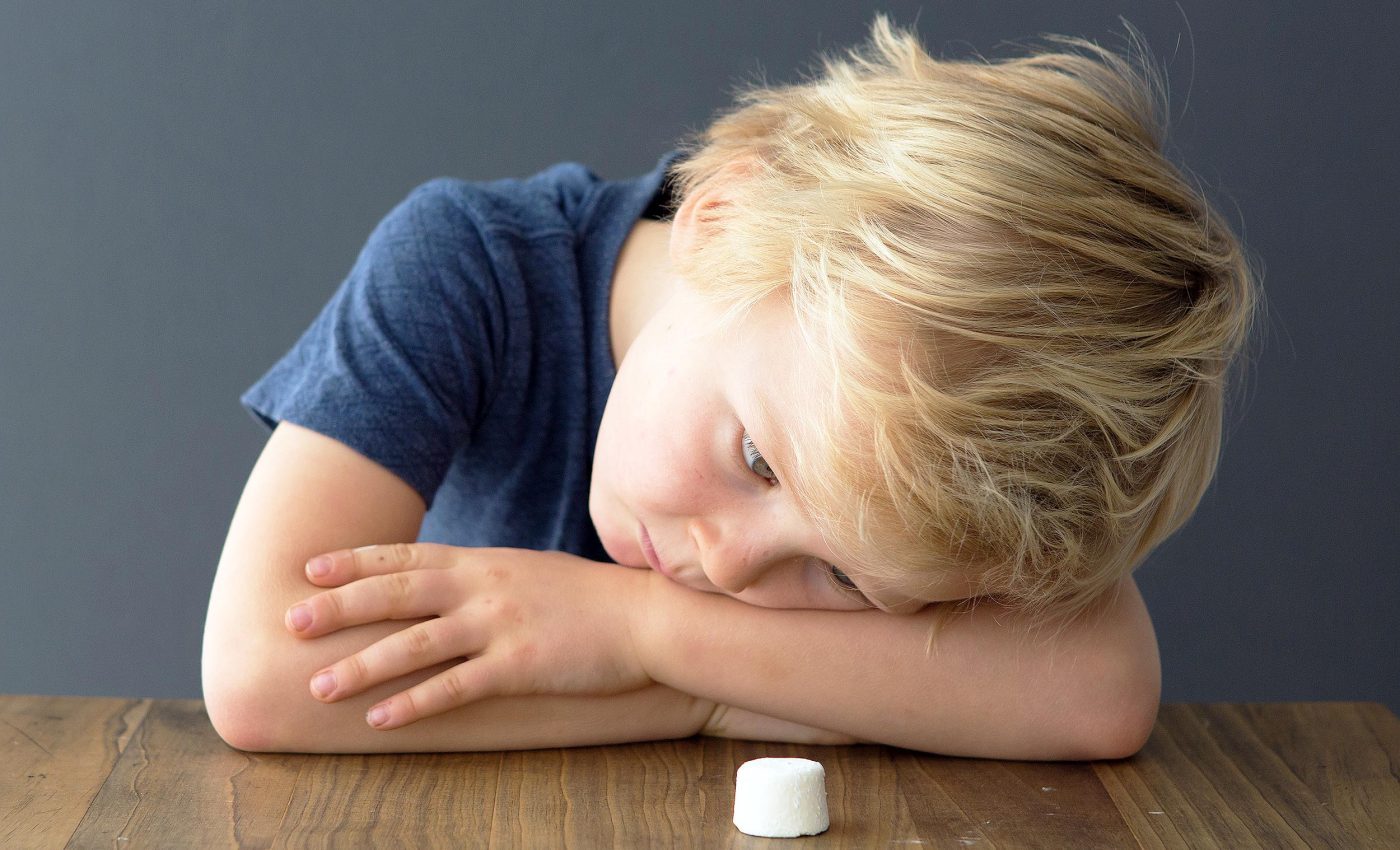
In 1970, a team of psychologists at Stanford designed a study to test the ability of a child to delay gratification, and then followed those children through adolescence to see whether their ability delay gratification had any correlation to lifelong success. In popular culture we know this as “The Marshmallow Test”, where the children who delayed the reward, (i.e. the marshmallow) had better success in adulthood. But the actual findings of the studies are more complex than what is purported. The researchers found that delayed gratification is actually suppressing the thought of the reward, rather than dealing with the frustration of delaying the reward. The most effective tool in delayed gratification is being able to cope with the thought of delaying the reward by avoiding the frustration altogether.
So, why am I sharing this and what does this have to do with market selloffs, you might ask?
Over the last month the market has gone from sanguine to outright manic-depressive. The tariff-war that the current administration has embarked upon has created most of the volatility, but one could argue that the market was due for some volatility going into the month of April. That extreme volatility has created some panic, and the panic has created some frustration. When this happens, the investor has a marshmallow sitting on the table in front of them, and that marshmallow is the ‘sell button’. Selling makes all the pain go away — but it leads to bad outcomes; like missing the powerful post-correction comebacks.
The way I deal with market selloffs is simple, I pay almost no attention to financial news, maybe 10 to 20 minutes a day. I read a handful of articles to get a handle on the important variables, and then I take a deep breath and cogitate on how things will likely unfold. Here is an example of how I would work through something like a trade war: The leader of a nation wants to impose tariffs on other nations and the market is unhappy with this proposal.
- First, I think about what this means for the economy, defining a worst-case and best-case scenario.
- Second, I think about the likelihood of each scenario in relation to both the economy and market.
- The last thing I do is make a decision about how my assets might be affected by each scenario.
Notice that during this process I am only thinking through the problem, not reacting to the market’s volatility. Once I have run through the mental gymnastics above, I feel well equipped to respond to any new piece of information that comes as the panic subsides.
From a high level, all investing is a big marshmallow test, we delay the gratification of a dollar today so we can compound that dollar for greater utility tomorrow. When stocks go up, the job of delaying gratification becomes easier, but when stocks go down, the gratification binary is flipped on its head. When the pain of loss hits our cerebral tissue the first response is to sell- the marshmallow makes everything better. This response is precisely the opposite of what an investor should do, the only way the investor makes money is buying low and selling high. The marshmallow is always the bait for the investor; we have to be very careful that we are not gratifying our most basic instincts of fear and greed in both good and bad markets.
Effectively, this is the best way to deal with markets, and it avoids the frustration of staring at the marshmallow for weeks or even months.
The opinions voiced in this material are for general information only and are not intended to provide specific advice or recommendations for any individual. All performance referenced is historical and is no guarantee of future results. All investing involves risks including loss of principal. No strategy assures success or protects against losses.
The economic forecasts set forth in this material may not develop as predicted and there can be no guarantee that strategies promoted will be successful.
The information presented is for educational and informational purposes only and is not intended as a recommendation or specific advice. Cryptocurrency and cryptocurrency-related products can be volatile, are highly speculative and involve significant risks including: liquidity, pricing, regulatory, cybersecurity risk, and loss of principal.